Gas Station Business Loans
The fuel business runs on volume. Your financing should keep up with it.
Get $5,000–$10,000,000 to replace equipment, finance fuel inventory, renovate your c-store, and cover compliance upgrades, funded in as little as 24 hours.
Simple, fast, and clear


How Gas Station Business Financing Works
Gas stations are high-volume and low-margin, a combination most traditional lenders don’t fully understand. Fuel distributors typically extend credit terms of 7 to 15 days. You need fuel in the ground before a single gallon is sold, and your margin on each gallon may be less than ten cents. The equipment that keeps a station running, from dispensers and underground storage tanks (USTs) to POS systems and car wash machinery, is expensive, subject to strict EPA and state compliance requirements, and rarely fails at a convenient time. In practice: it’s mid-October, your busiest season is approaching, and locking in a higher-volume fuel contract requires an upfront inventory purchase roughly $40,000 above your typical order. At the same time one of your four dispensers is throwing error codes and needs replacing before winter, at $18,000 installed. Your daily revenue is steady, but your cash position doesn’t cover both at once, and your supplier’s payment clock starts the moment the tanker leaves. SBG Funding provides $5,000 to $10,000,000, with same-day decisions.
SBG Funding structures financing around how gas stations actually operate. A business line of credit revolves against fuel inventory purchases and recurring operating costs: draw when a supplier payment is due, repay as daily revenue comes in, and draw again on the next cycle. A business term loan is a lump sum for planned investments such as dispenser replacements, canopy upgrades, or a full convenience store renovation. Equipment financing is structured for major equipment purchases, with longer repayment terms that align with the equipment’s useful life.
Traditional banks evaluate gas stations conservatively: high fuel inventory costs, environmental liability exposure and thin margins make them a difficult fit for conventional lending. A bank underwrites against two years of filed financials and a 680 credit score. Banks are not built to underwrite against margins measured in cents on volume, which means the businesses under the most cash flow pressure are the ones a bank is slowest to serve. SBG Funding evaluates your revenue, deposit history and ability to repay; our unsecured products require no collateral and we never perform a hard credit pull.
See How We Stack Up
Traditional Bank
Typical Online Lender
Won't affect your credit score.
Gas Station Financing for Every Situation
The right financing depends on what your station needs right now.
Equipment Failure (Dispensers, Tanks, and POS Systems)
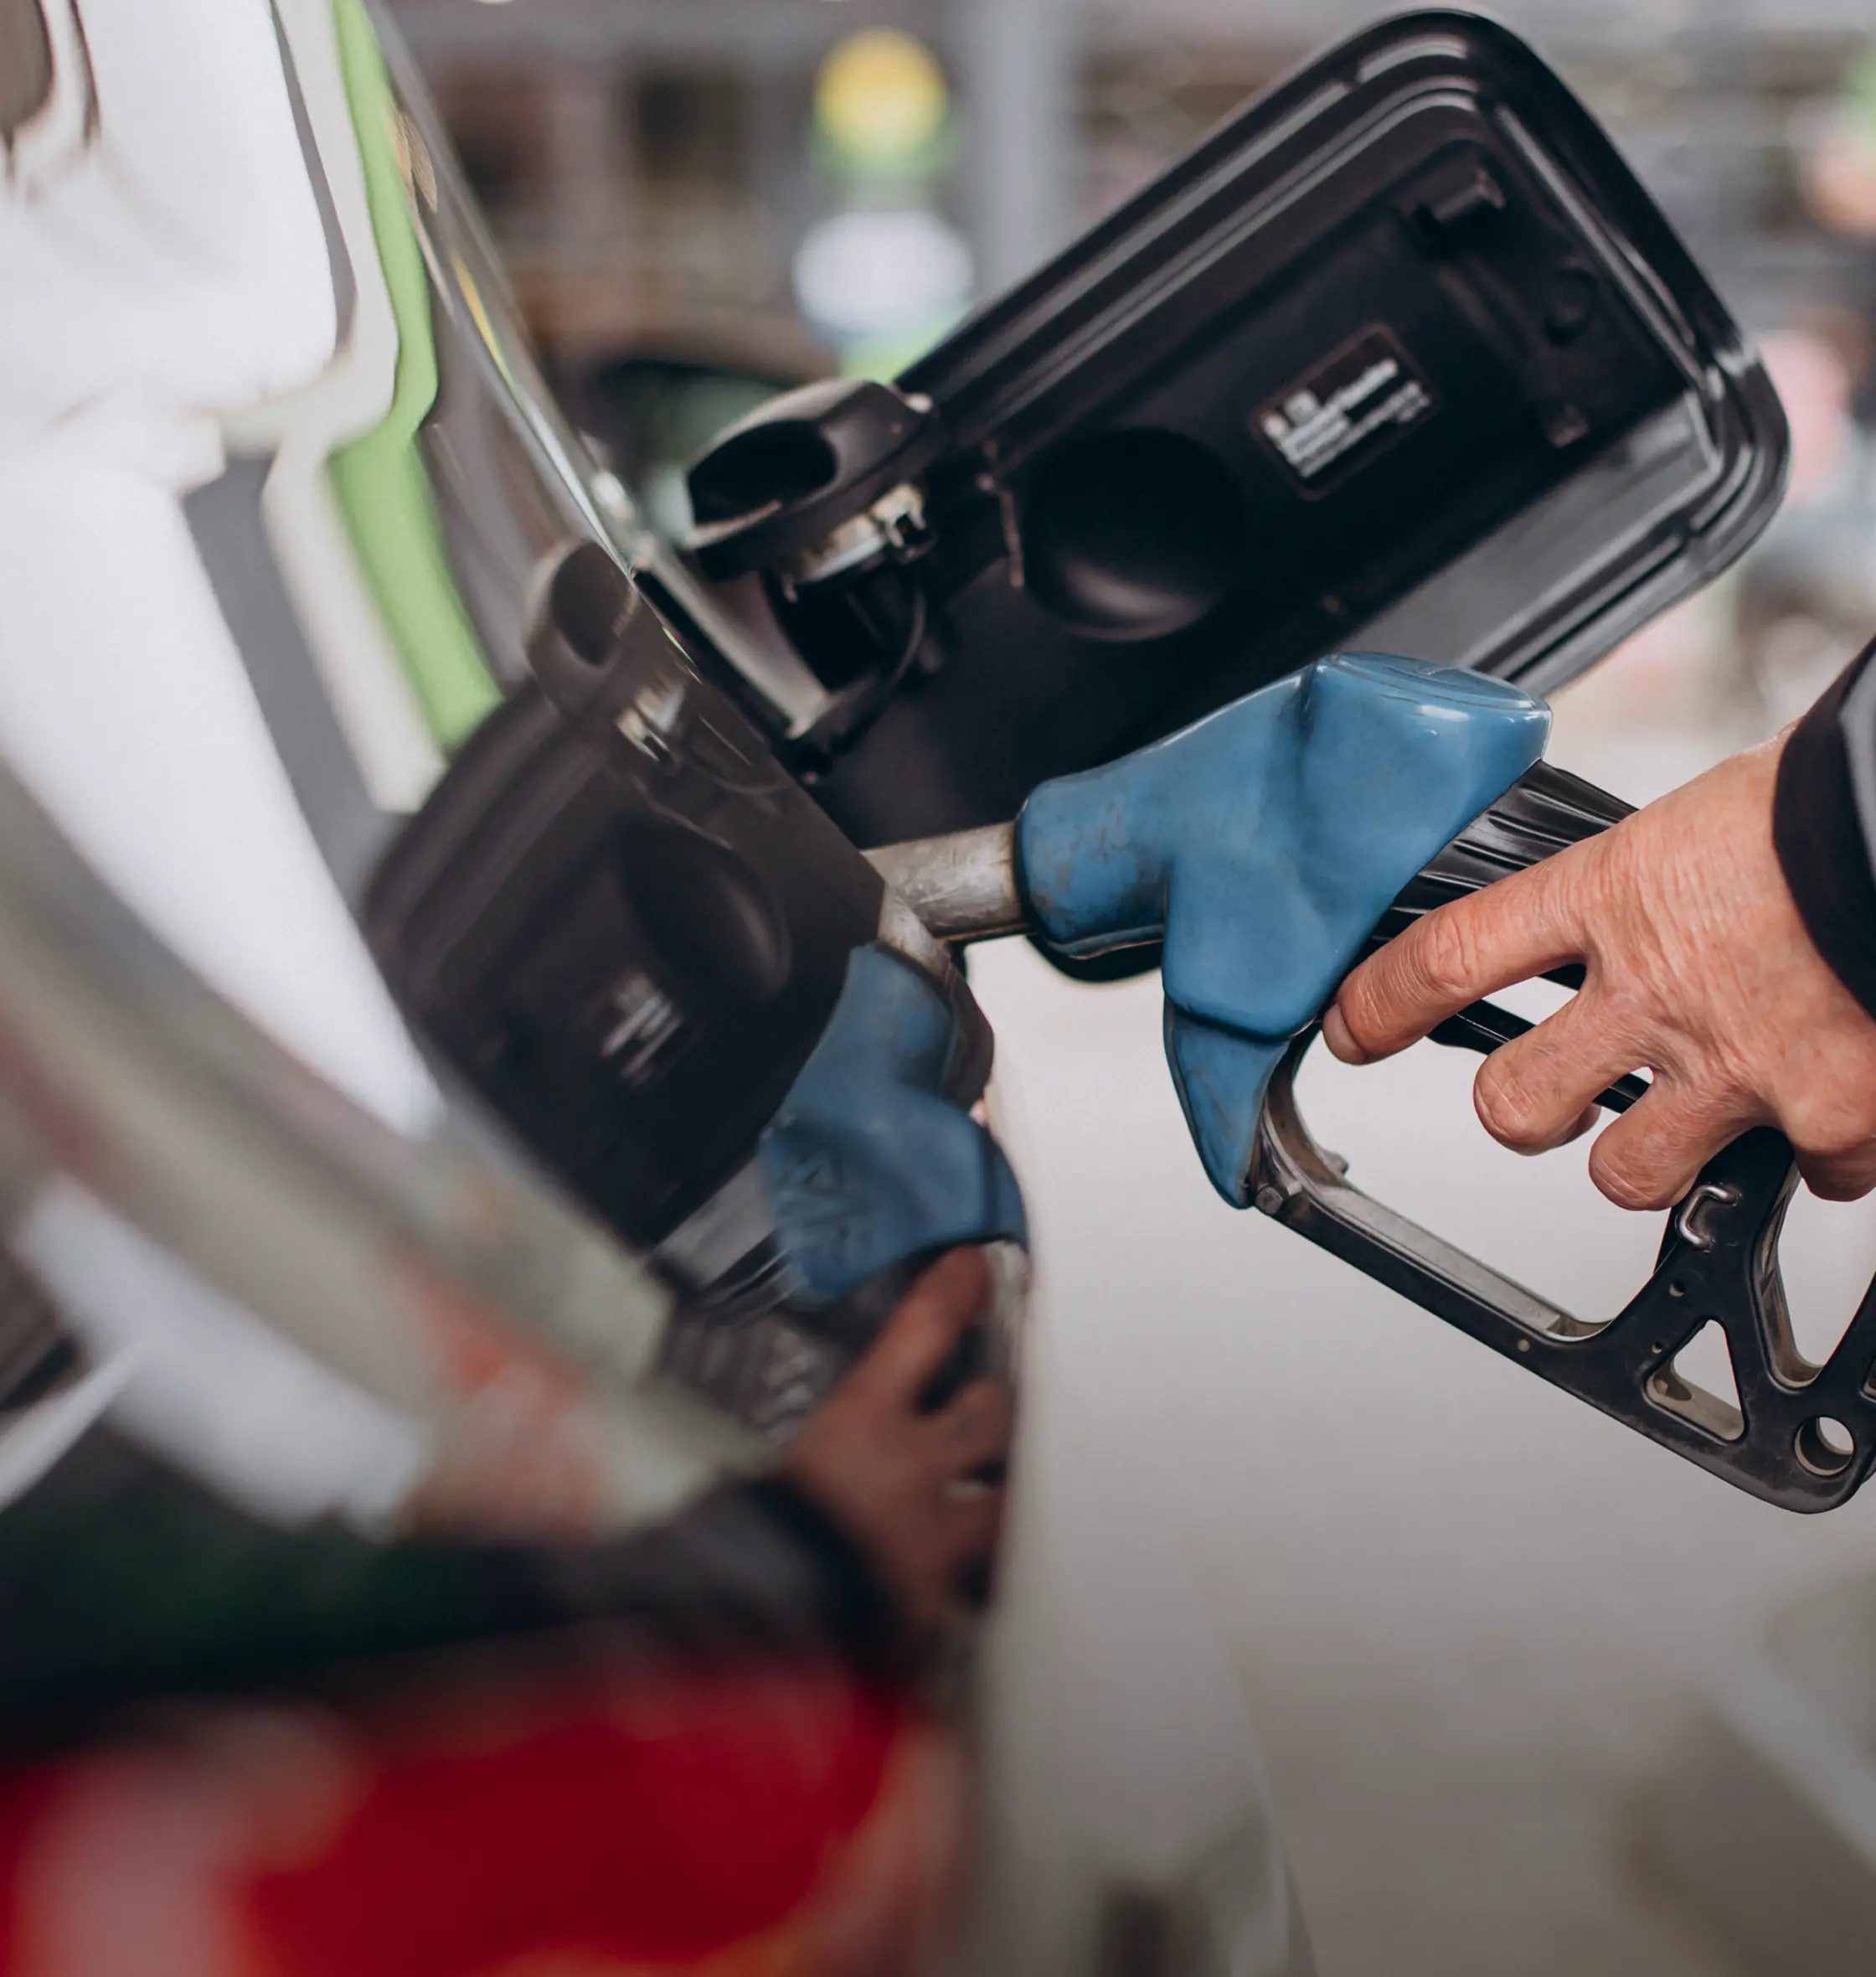
A dispenser that’s down is a pump not generating revenue. EPA and state regulations mean you can’t defer UST maintenance indefinitely. When equipment fails or compliance deadlines approach, you need capital fast. A business term loan or equipment financing gets you the funds to repair or replace equipment quickly, before the downtime compounds the cost.
Fuel distributors don’t wait for your daily revenue to catch up. When a payment is due or you want to lock in volume pricing ahead of a busy period, you need working capital available. A business line of credit gives you revolving access to funds for inventory purchases, draw when supplier payments are due, repay as transactions clear, repeat.
Your convenience store generates significantly better margins than your fuel sales. Investing in a renovation, updated product mix, or expanded food service offering can meaningfully improve your station’s overall profitability. A business term loan funds the renovation without disrupting the operating capital you need to keep the fuel side running. If you are buying the site outright and SBA financing is in underwriting, bridge capital covers the closing while the SBA facility finalizes.
What Gas Station Owners Use Business Loans For
Gas station financing is flexible. Here are the most common ways owners put it to work.
All you need to Qualify
- No collateral
- No hard credit pull
- No upfront fees.
SBG Funding evaluates more than 50 factors when making lending decisions, including revenue history, deposit consistency, and time in business. Gas station businesses with strong cash flow may qualify even with an imperfect credit score.
Applying will not impact your credit score.
$150K+
annual revenue
500+
min. FICO score
6+
months in business
4
bank statements
Applying will not impact your credit score.
“Andrew was quick to respond to our initial request for a business loan. He was able to explain the different loan options available. He answered our questions and was able to fund our loan quickly. Andrew was very professional and helped to make the process go smoothly.”

$3B+
Funded since 2017

via Trustpilot
George was very helpful, responsive and friendly. He secured the perfect funding for our business. He was fast, friendly and efficient.
4.9
Trustpilot rating

5×
Inc. 5000 honoree
via Better Business Bureau
He explained the process so well. It was quick and easy. He walked me through every step of the way!
85%
Approval rate
via Better Business Bureau
Other than being pleasant to chat with, he was on top of communicating all the important things with me, and wasted no time when we could proceed to the next step :)
A
BBB rating
via Better Business Bureau
He was way more on top of everything than I was and guided me through the process like a real pro.
4.9
Google rating
via Better Business Bureau
He was very accessible and knowledgeable about the options that would work for my company. He made the entire process seamless.
Just 3 Steps to Get Funded
Apply Online
Complete our quick online application in about 5 minutes. Basic information about your business and financing needs, no lengthy paperwork to get started.
Get Approved
Our team reviews your application and presents financing options matched to your business profile. We look at revenue, deposit history, and time in business, not just your credit score.
Receive your funds
Once approved and documents are signed, funds can be in your business bank account in as little as 24 hours.
Frequently Asked Questions
SBG Funding requires a minimum FICO score of 500. Credit score is one factor among many. Strong revenue, consistent bank deposits, and solid time in business can all support your application. Gas station owners with scores between 500 and 620 have qualified based on high transaction volume and consistent daily deposits.
Helpful: 0 / Not helpful: 0
After approval and document submission, funds can be available in as little as 24 hours. The online application takes about 5 minutes, and most applicants receive a decision the same business day.
Helpful: 0 / Not helpful: 0
No. SBG Funding’s gas station loans are unsecured. You are not required to pledge your property, equipment, or other assets. Two exceptions: equipment financing is secured by the equipment itself, and SBA 7(a) financing may require collateral, which is standard across the industry.
Helpful: 0 / Not helpful: 0
Yes. SBG Funding works with independent station owners and franchise operators alike. Brand affiliation does not affect eligibility. What matters is your business revenue, time in operation, and overall financial health, not whether you’re flying a major fuel brand’s flag.
Helpful: 0 / Not helpful: 0
Yes. Dispenser replacement is one of the most common uses of gas station business financing. Equipment financing and business term loans are both well suited for this, equipment financing typically offers longer repayment terms, while a business term loan provides flexibility if you’re combining the dispenser purchase with other improvements.
Helpful: 0 / Not helpful: 0
Yes. A business line of credit is the best fit for recurring fuel inventory costs. It gives you revolving access to working capital. Draw when a supplier payment is due, repay it as daily transactions clear, and draw again on the next reorder cycle. You only pay interest on what you use.
Helpful: 0 / Not helpful: 0
Yes. Underground storage tank maintenance, leak detection upgrades, and EPA compliance work are eligible uses of business financing. Regulatory deadlines don’t wait, and a business term loan can be funded fast enough to meet compliance timelines without disrupting your operating cash flow.
Helpful: 0 / Not helpful: 0
Yes. C-store renovations, including layout updates, food service additions, cooler replacements, and exterior signage, are a common use of gas station business loans. A business term loan provides a lump sum upfront, with repayment structured around the improved revenue the renovation generates.
Helpful: 0 / Not helpful: 0
Seasonal variation is common in the fuel industry and does not disqualify your application. SBG Funding evaluates annual revenue consistency and overall deposit patterns, not individual slow months. If your station performs well over a full year, seasonal dips are expected and factored into how we assess your application.
Helpful: 0 / Not helpful: 0
Ready to Keep Your Station Running?
Whether you need to replace a dispenser, cover a fuel inventory payment, or renovate your convenience store, SBG Funding has financing options built for how gas stations actually operate. Apply online in minutes. No collateral, no hard credit pull, no obligation.