HVAC Business Loans
New equipment. Slow season. Crew to pay. The timing never lines up.
Get $5,000–$10,000,000 to purchase equipment, cover payroll through slow seasons, and take on larger commercial installs, funded in as little as 24 hours.
Simple, fast, and clear


How HVAC Financing Works
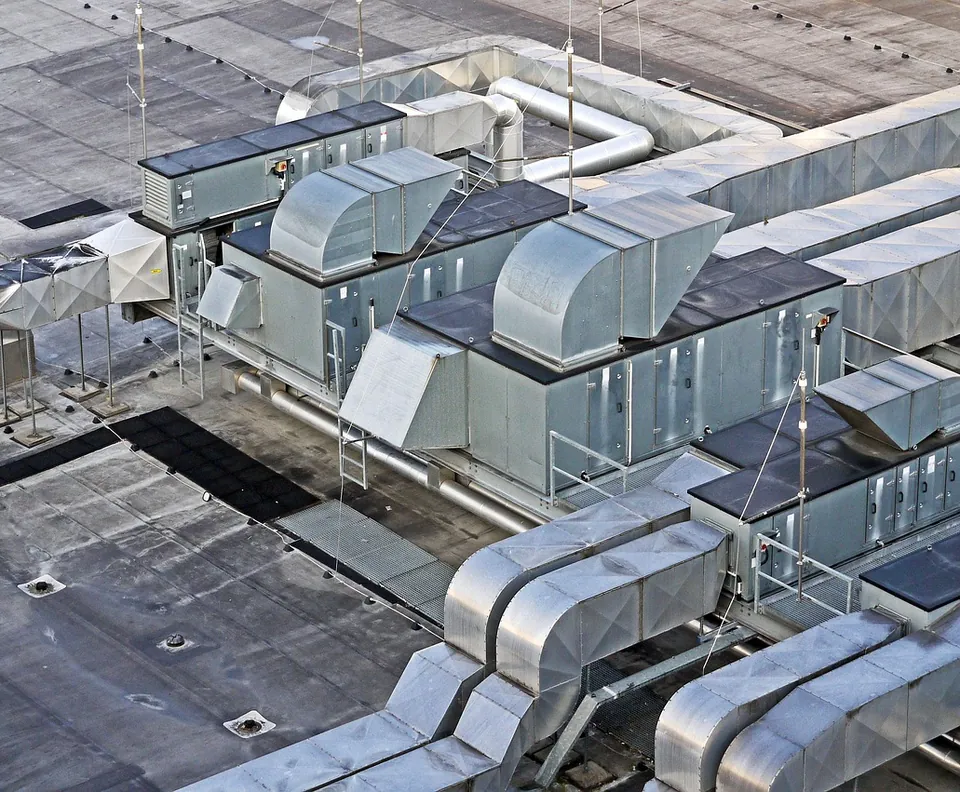
HVAC businesses run on two overlapping cash flow pressures. The first is seasonality: demand spikes in summer and winter, drops sharply in spring and fall, and fixed costs like payroll, insurance and vehicle payments don’t adjust with it. The second is job timing: you order equipment and materials upfront, schedule your crew, complete the install, and then wait. Residential customers pay at completion; commercial clients pay on net-30 or net-60 terms. In practice: it’s February, and your busiest months, July, August and January, are behind you or months away. You have a crew of six on payroll. A commercial property manager just approved a $60,000 multi-unit install starting in three weeks, your biggest job of the quarter. You need to order the equipment now: the deposit covers part of it, the balance is due on delivery, and your slow-season cash position can’t front the rest. The job is real. The timing is the problem. SBG Funding provides $5,000 to $10,000,000, with same-day decisions.
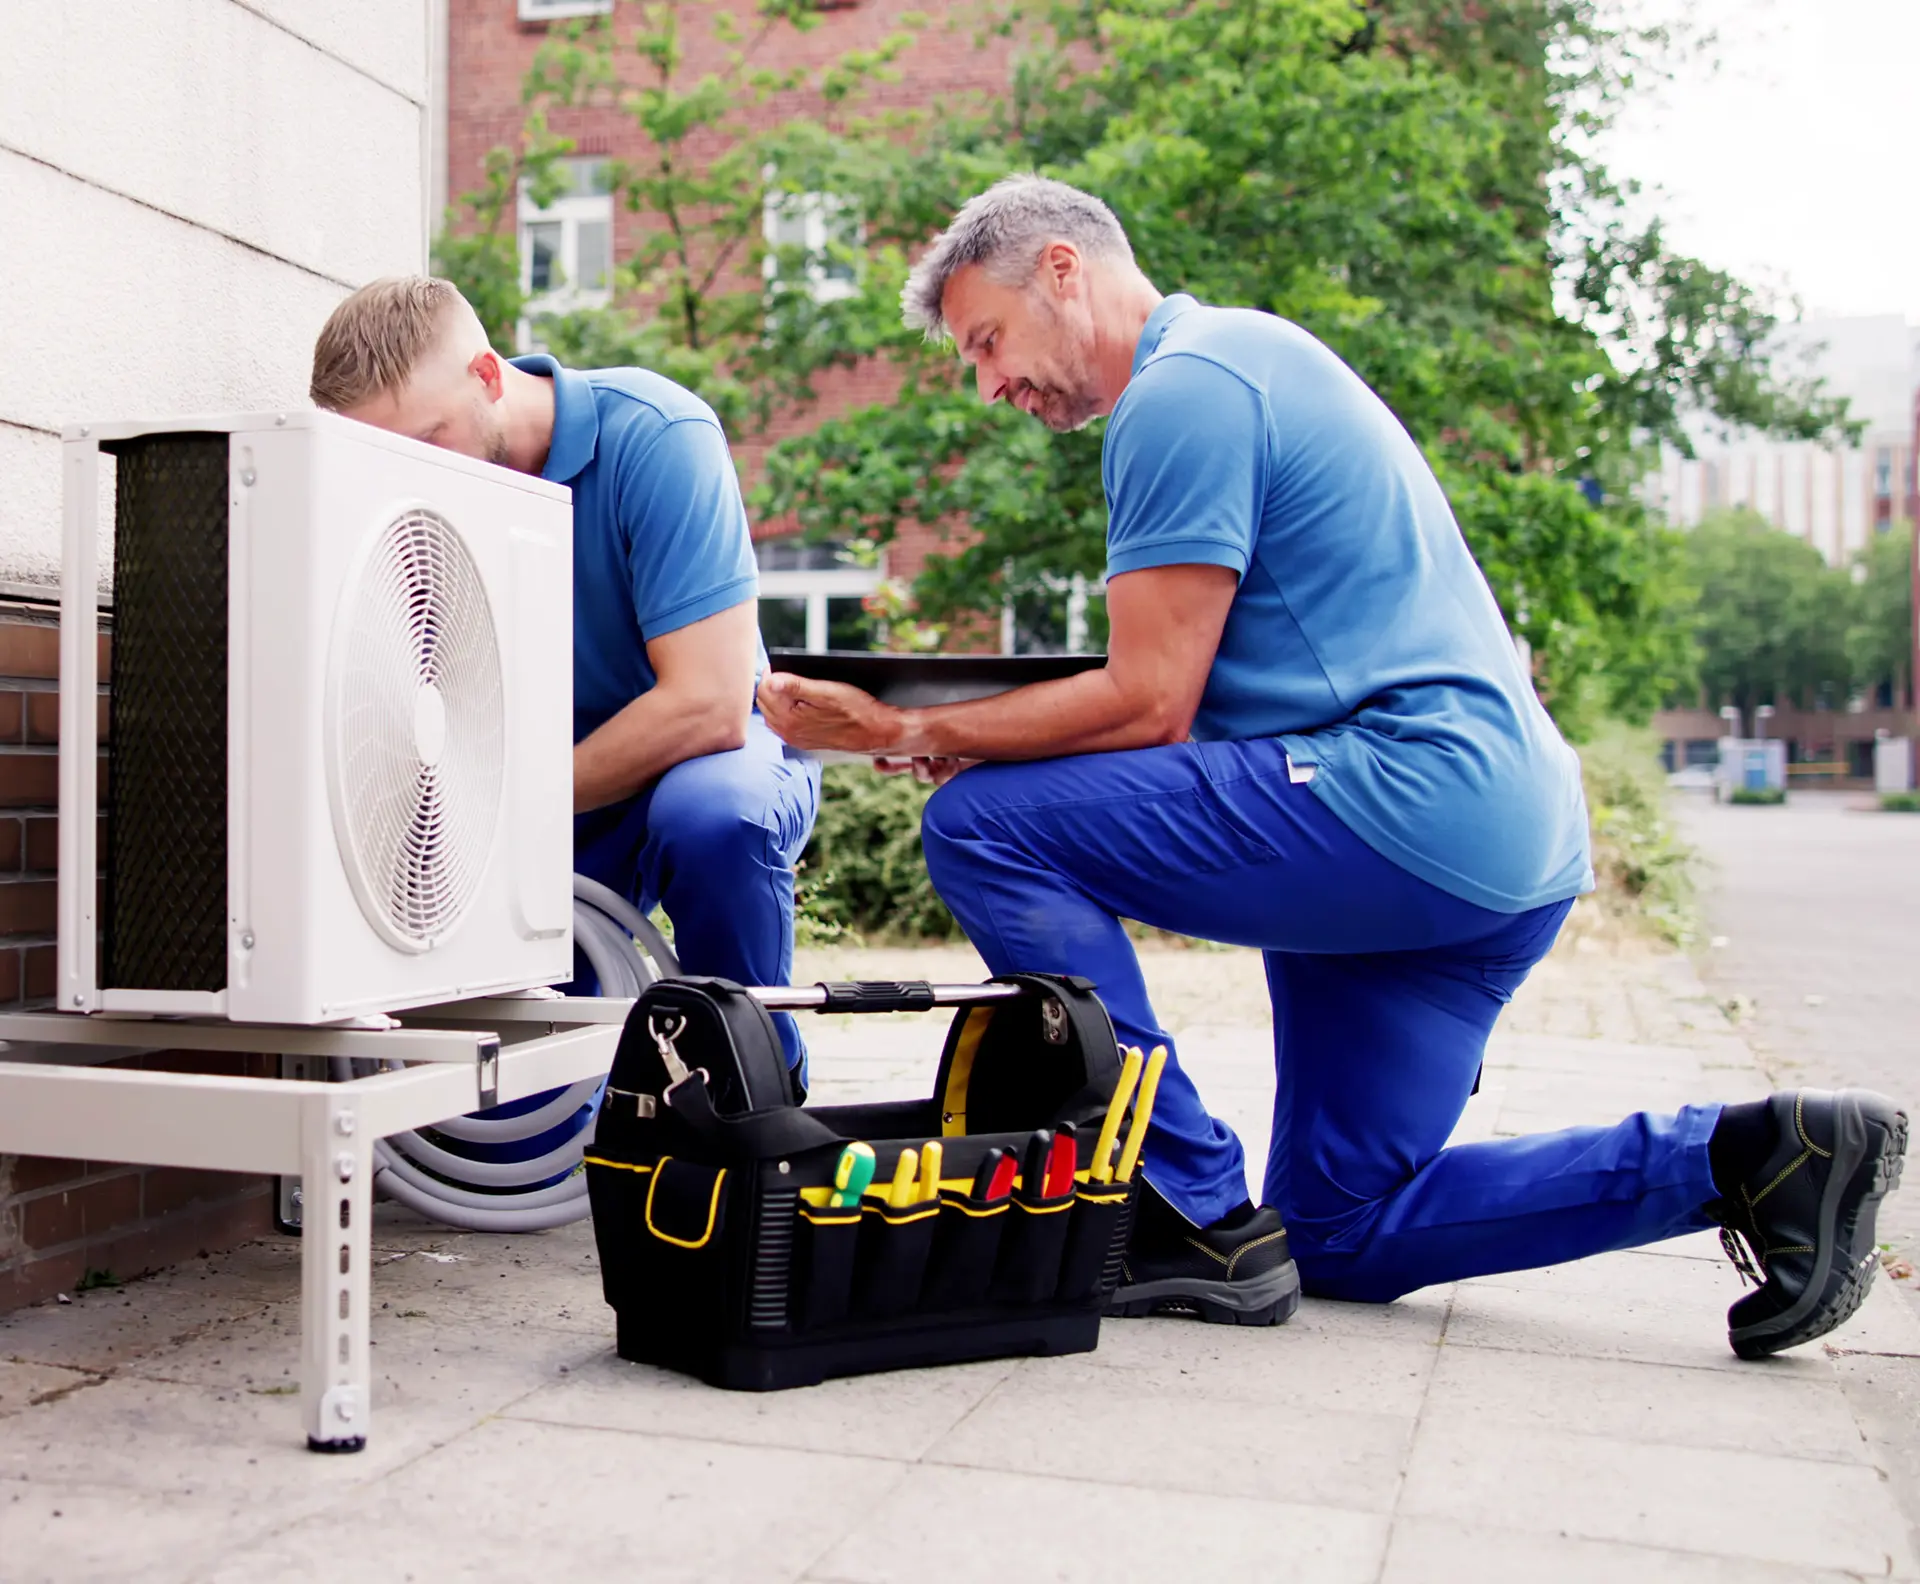
SBG Funding structures financing around how HVAC businesses actually operate. A business line of credit revolves: draw to cover payroll and operating costs during slow months, repay when busy-season revenue lands, and draw again the following off-season. A business term loan is a lump sum for larger investments, such as a new service vehicle, a major equipment order, or the capital to take on a commercial contract your cash position can’t support. Equipment financing acquires HVAC systems, diagnostic tools and specialty equipment without tying up your working capital.
A bank underwrites against two years of filed financials and a 680 credit score, which is why a fully booked contractor coming out of a slow spring can still be declined. Banks are not built to underwrite against revenue that arrives unevenly, or on net-60 terms after a commercial install, which means the businesses under the most cash flow pressure are the ones a bank is slowest to serve. SBG Funding’s unsecured products require no collateral and we never perform a hard credit pull.
See How We Stack Up
Traditional Bank
Typical Online Lender
Won't affect your credit score.
HVAC Financing for Every Situation
The right financing depends on what your business needs right now.
Covering Payroll Through the Slow Season
Spring and fall are the reality check for HVAC cash flow. Call volume drops, but your technicians, office staff, and fixed overhead don’t. A business line of credit gives your company revolving access to working capital to cover payroll and operating costs during low-demand months, draw what you need, repay it when your busy season kicks in, and draw again the following slow period.
Purchasing Equipment or Adding a Service Vehicle
New HVAC systems, diagnostic equipment, and service vehicles are among the largest capital outlays an HVAC company makes, and they often need to be purchased before the revenue from the jobs they’ll support has arrived. Equipment financing and business term loans let you acquire the equipment your business needs without draining the working capital you rely on to keep current jobs moving.
Taking On a Large Commercial Contract
Commercial HVAC installs on multi-unit properties, office buildings and industrial facilities are the highest-margin jobs in the industry. They’re also the most capital-intensive: equipment ordered weeks before install, labor costs upfront, and payment on net-30 or net-60 terms after completion. A business term loan or invoice financing gives you the capital to take on large commercial jobs without disrupting the residential work that keeps the lights on.
What HVAC Companies Use Business Loans For
HVAC financing is flexible. Here are the most common ways HVAC contractors put it to work.
All you need to Qualify
- No collateral
- No hard credit pull
- No upfront fees.
SBG Funding evaluates more than 50 factors when making lending decisions, including revenue history, deposit consistency, and time in business. HVAC businesses with strong cash flow may qualify even with an imperfect credit score.
Applying will not impact your credit score.
$150K+
annual revenue
500+
min. FICO score
6+
months in business
4
bank statements
Applying will not impact your credit score.
“It was a straightforward, streamlined experience with great service. He answered all questions directly, with no ambiguous responses. Would recommend and use again should there be a need in the future for other capital needs.”

$3B+
Funded since 2017

via Trustpilot
I worked with Dylan to get funded. He was very professional and a very hard worker. Wouldn’t stop until the right funding company came available. Very highly recommended. Will use him again for future funding.
4.9
Trustpilot rating

5×
Inc. 5000 honoree
via Better Business Bureau
You can tell he cares about his clients and getting them the best deal they feel confident in. Definitely gonna be my go to guy.
85%
Approval rate
via Trustpilot
Casey was a true professional. I applied online with their super simple application and was approved for a business line of credit literally within minutes, in less than one hour. This was after being turned down by my bank because my company had only been in business 12 months. Casey walked me through the setup and the money was in my account the following day. 5 stars all the way for being a pro and keeping it so simple.
A
BBB rating
via Better Business Bureau
His support and dedication made a big difference, and I truly appreciate his commitment to making sure everything was taken care of. Highly recommend.
4.9
Google rating
via Better Business Bureau
He helped me navigate all of my needs and get exactly the type of funding I was looking for. He did a great job explaining and answering any questions I had as well. 5 Stars for sure!!
Just 3 Steps to Get Funded
Apply Online
Complete our quick online application in about 5 minutes. Basic information about your business and financing needs, no lengthy paperwork to get started.
Get Approved
Our team reviews your application and presents financing options matched to your business profile. We look at revenue, deposit history, and time in business, not just your credit score.
Receive your funds
Once approved and documents are signed, funds can be in your business bank account in as little as 24 hours.
Frequently Asked Questions
SBG Funding requires a minimum FICO score of 500. Credit score is one factor among many. Strong revenue, consistent bank deposits, and solid time in business can all support your application. Many HVAC contractors with scores between 500 and 620 have qualified based on strong seasonal deposit history.
Helpful: 0 / Not helpful: 0
After approval and document submission, funds can be available in as little as 24 hours. The online application takes about 5 minutes, and most applicants receive a decision the same business day.
Helpful: 0 / Not helpful: 0
No. SBG Funding’s HVAC business loans are unsecured. You are not required to pledge vehicles, equipment, or other assets. Equipment financing is an exception: the equipment itself serves as collateral, which is standard across the industry.
Helpful: 0 / Not helpful: 0
Yes. Seasonal revenue is the norm in HVAC, and SBG Funding evaluates your full annual revenue history rather than your current month’s cash position. A strong summer or winter season, consistent deposit patterns, and solid annual revenue are the factors that matter most. Many HVAC companies use a business line of credit specifically because it can be drawn during slow months and repaid during peak seasons.
Helpful: 0 / Not helpful: 0
SBG Funding works with residential and commercial HVAC contractors, mechanical contractors, refrigeration service companies, plumbing and HVAC combinations, and specialty trades including ductwork, boiler service, and building controls. As long as your business meets the basic requirements of 6+ months in operation, $150K+ annual revenue and 500+ FICO, your service mix does not affect eligibility.
Helpful: 0 / Not helpful: 0
Yes. Both business term loans and dedicated equipment financing can be used to purchase HVAC systems, units, diagnostic tools, and service vehicles. Equipment financing often supports longer repayment terms for larger purchases such as up to 5 years, and uses the equipment itself as collateral.
Helpful: 0 / Not helpful: 0
Yes. Commercial contracts are one of the primary use cases for HVAC business financing. Large installs require significant upfront costs, equipment ordered and delivered before work begins, labor across multiple days or weeks, and materials purchased in bulk. A business term loan provides the lump-sum capital to execute a commercial job without disrupting your residential pipeline.
Helpful: 0 / Not helpful: 0
Yes. Commercial HVAC clients such as property managers, general contractors and facilities teams typically pay on net-30 or net-60 terms. Invoice financing lets you unlock the value of an outstanding invoice immediately rather than waiting on your customer’s payment cycle. This keeps working capital available for the next job without taking on long-term debt.
Helpful: 0 / Not helpful: 0
Your business must have been in operation for at least 6 months to qualify for most SBG Funding programs. If you’re in your first 6 months, we recommend applying once you’ve crossed that threshold with consistent monthly revenue. HVAC companies that hit the ground running with strong early deposit history may qualify at or shortly after the 6-month mark, contact us to discuss your situation.
Helpful: 0 / Not helpful: 0
Ready to Grow Your HVAC Business?
Whether you need to cover payroll through a slow season, purchase equipment for a large commercial install, or add a service vehicle to expand your capacity, SBG Funding has HVAC financing options built for how contractors actually operate. Apply online in minutes. No collateral, no hard credit pull, no obligation.