Restaurant Business Loans
Your tables fill up on weekends. Your bills don’t wait for them.
Get $5,000–$10,000,000 to cover payroll, purchase kitchen equipment, fund renovations, and grow your restaurant, funded in as little as 24 hours.
Simple, fast, and clear


How Restaurant Business Financing Works
Restaurants operate on one of the most unforgiving cash flow cycles in small business. Revenue arrives daily, but unevenly: a slow Wednesday can erase a strong Saturday, while food costs, labor, rent and utilities don’t flex with weekly sales. In practice: it’s mid-January, your slowest month, and your walk-in refrigeration unit breaks down. Replacing it costs $8,000. Your food distributor payment is due Friday, payroll is Monday, and December’s strong numbers aren’t sitting in the account. That isn’t a struggling restaurant. That’s Tuesday in the restaurant industry. SBG Funding provides $5,000 to $10,000,000, with same-day decisions.
SBG Funding structures financing around how restaurants actually operate. A business line of credit revolves: draw to cover payroll during slow weeks and repay when revenue picks back up. A business term loan is a lump sum for larger investments such as a kitchen renovation, a dining room refresh, or equipment that’s been on the wish list. Equipment financing acquires the commercial refrigeration, ranges and POS systems your kitchen depends on without draining working capital.
A bank underwrites against two years of filed financials and a 680 credit score, which is why a restaurant with a strong December can still be declined in January. Banks are not built to underwrite against revenue that arrives daily but unevenly, which means the businesses under the most cash flow pressure are the ones a bank is slowest to serve. SBG Funding’s unsecured products require no collateral and we never perform a hard credit pull.

See How We Stack Up
Traditional Bank
Typical Online Lender
Won't affect your credit score.
Restaurant Financing for Every Situation
The right financing depends on where your restaurant is right now.
Managing Cash Flow in Slow Seasons
Every restaurant has slow weeks, post-holiday January, the lull before summer, a rainy month that kills foot traffic. A business line of credit gives you revolving access to capital to cover payroll and operating costs during low-revenue periods without dipping into your own savings. Draw what you need, repay it when business picks up, and draw again.
Upgrading or Replacing Equipment
Commercial ranges, refrigeration units, dishwashers, and ventilation systems are among the largest capital outlays a restaurant faces, and they tend to fail at the worst possible time. Equipment financing and business term loans let you replace or upgrade critical kitchen equipment without a cash flow crisis, with repayment terms structured to fit your revenue cycle.
Expanding Your Operation
Whether you’re opening a second location, acquiring an existing restaurant, completing a dining room renovation, or launching a catering operation, growth in the restaurant industry requires significant upfront capital. A business term loan or SBA 7(a) financing provides the lump-sum funding to execute your expansion without disrupting your current operation. When a seller’s deadline lands before your SBA financing closes, bridge capital covers the acquisition and is repaid at closing.
What Restaurant Owners Use Business Loans For
Restaurant financing is flexible. Here are the most common ways restaurant owners and operators put it to work.
All you need to Qualify
- No collateral
- No hard credit pull
- No upfront fees.
SBG Funding evaluates more than 50 factors when making lending decisions, including revenue history, deposit consistency, and time in business. Restaurant businesses with strong cash flow may qualify even with an imperfect credit score.
Applying will not impact your credit score.
$150K+
annual revenue
500+
min. FICO score
6+
months in business
4
bank statements
Applying will not impact your credit score.
What Restaurant Owners Are Saying
Kinn Thai — Funded by SBG Funding
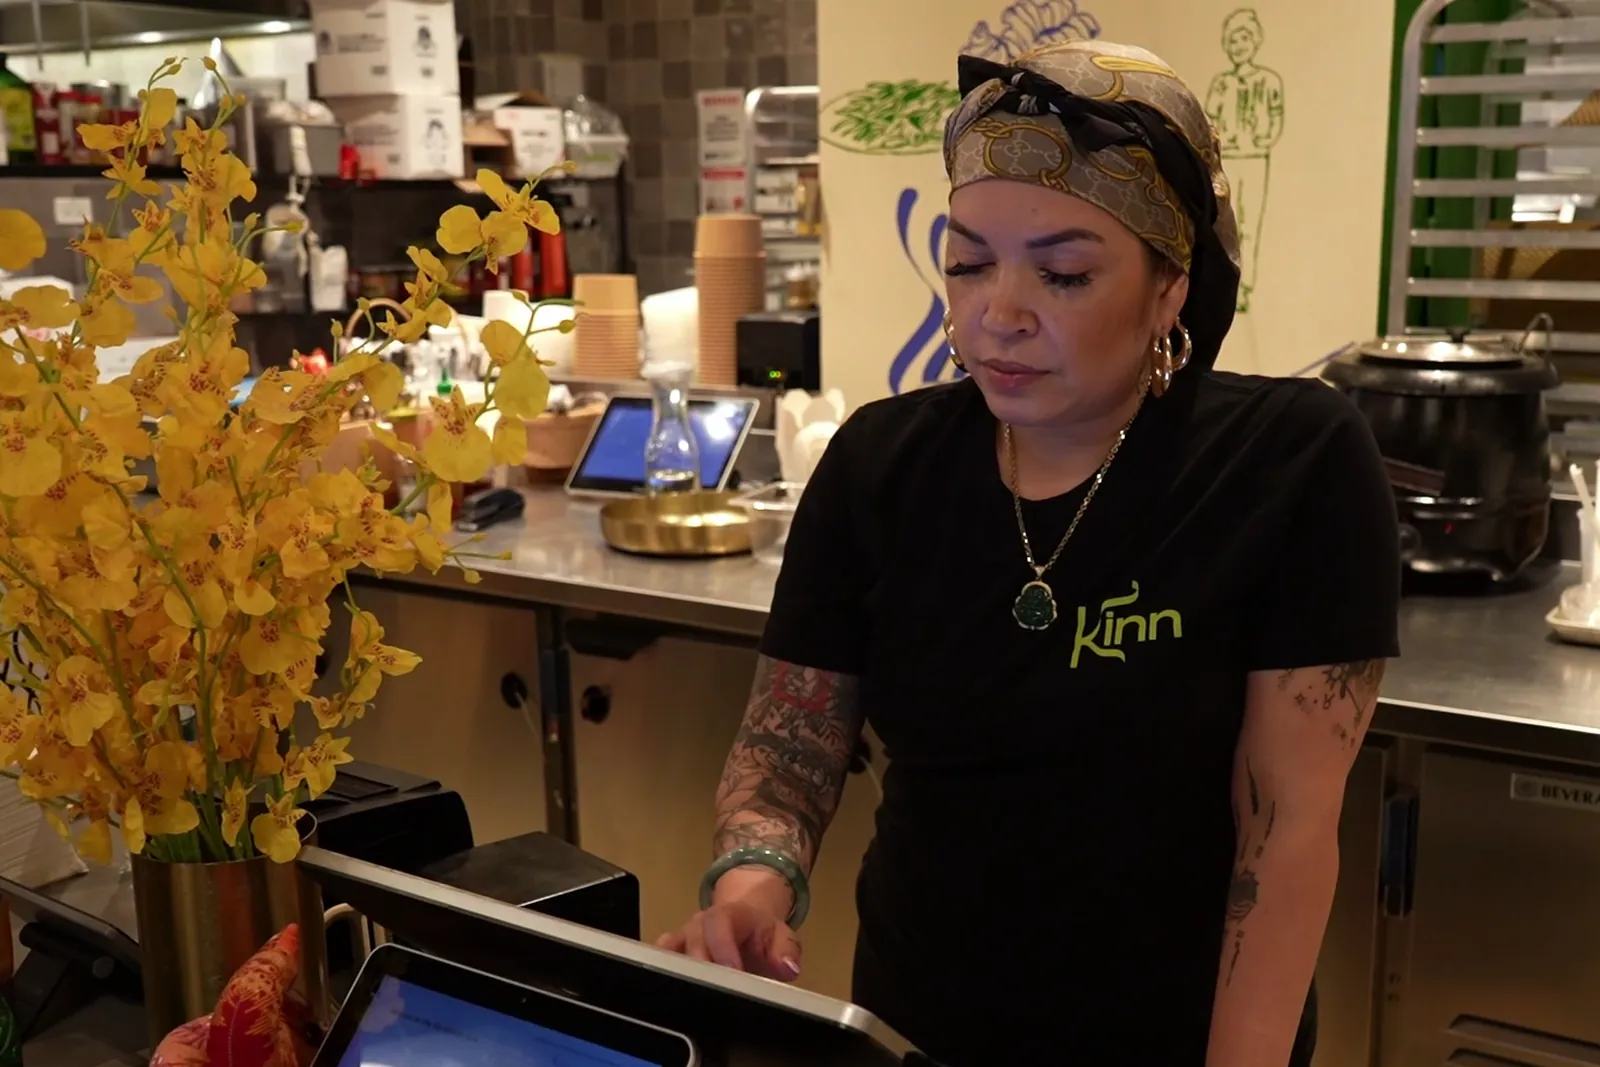
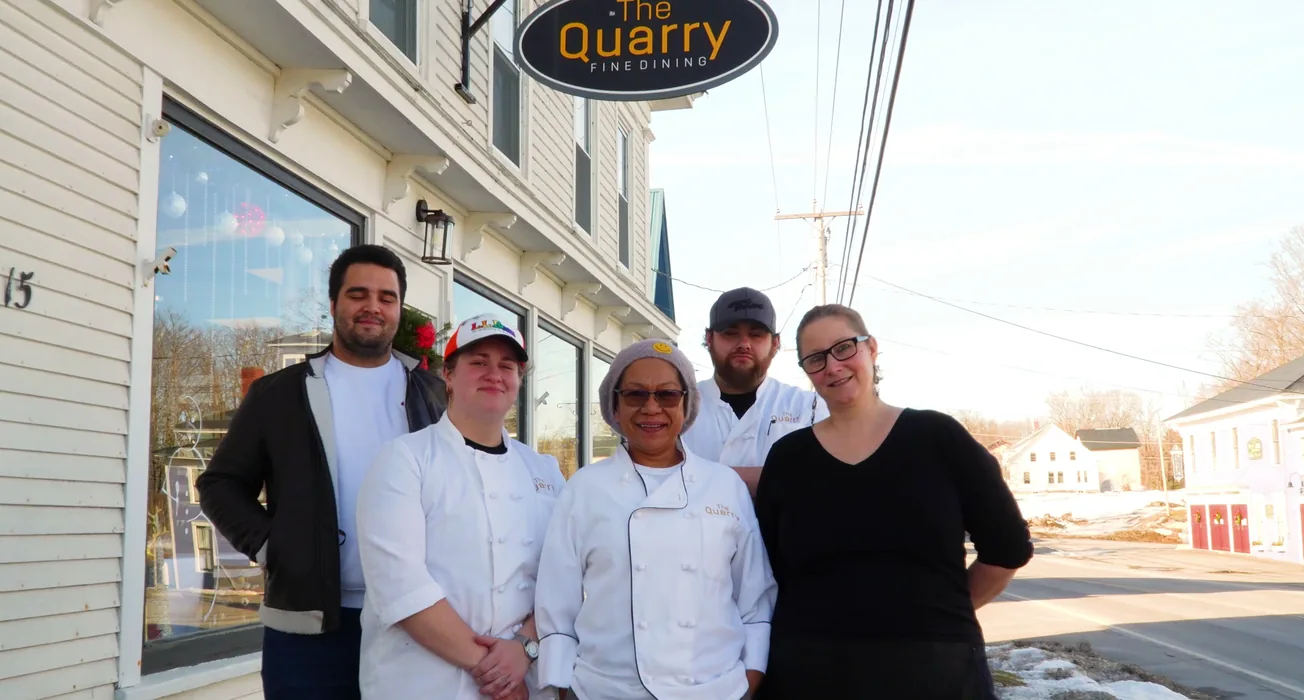
“The whole process with Cameron and his company, SBG Funding, has been a blessing to our small restaurant. Cameron assisted and made sure the loan process was very simple and easy.”

$3B+
Funded since 2017

via Trustpilot
Nick Chalfen was great. He was very thorough with the process. Great communication throughout the whole process.
4.9
Trustpilot rating

5×
Inc. 5000 honoree
via Better Business Bureau
She made the process effortless. She also walked me through the process being patient and helpful. She also checked on everything after. Highly recommend her.
85%
Approval rate
via Better Business Bureau
It was a simple, straightforward process and I felt like products were in line for my needs and not forced on me. Thanks again for being a part of my business’s future growth.
A
BBB rating
via Better Business Bureau
He went above and beyond to help us secure funding and guided us through the process with clarity, patience, and genuine care.
4.9
Google rating
via Better Business Bureau
Great to work with, made the experience of gaining necessary capital to continue growth an easy process.
Just 3 Steps to Get Funded
Apply Online
Complete our quick online application in about 5 minutes. Basic information about your business and financing needs, no lengthy paperwork to get started.
Get Approved
Our team reviews your application and presents financing options matched to your business profile. We look at revenue, deposit history, and time in business, not just your credit score.
Receive your funds
Once approved and documents are signed, funds can be in your business bank account in as little as 24 hours.
Frequently Asked Questions
SBG Funding requires a minimum FICO score of 500. Credit score is one factor among many. Strong revenue, consistent bank deposits, and solid time in business can all support your application. Many restaurant owners with scores between 500 and 620 have qualified based on strong daily deposit history.
Helpful: 0 / Not helpful: 0
After approval and document submission, funds can be available in as little as 24 hours. The online application takes about 5 minutes, and most applicants receive a decision the same business day.
Helpful: 0 / Not helpful: 0
No. SBG Funding’s restaurant business loans are unsecured. You are not required to pledge equipment, real estate, or other assets. Equipment financing is an exception: the equipment itself serves as collateral, which is standard across the industry.
Helpful: 0 / Not helpful: 0
Yes. Seasonal swings are normal in this industry and we underwrite for them. Approval rests on your deposit history across the whole year rather than your slowest month, so a strong season carries a weak one. A business line of credit is usually the better structure for a recurring seasonal gap, because you draw during the slow months and repay when trade picks up rather than carrying a fixed balance year-round.
Helpful: 0 / Not helpful: 0
SBG Funding works with full-service restaurants, fast casual and quick service concepts, bars and breweries, food trucks, catering companies, and multi-location dining groups. As long as your business meets the basic requirements of 6+ months in operation, $150K+ annual revenue and 500+ FICO, your restaurant type does not affect eligibility.
Helpful: 0 / Not helpful: 0
Yes. Both business term loans and dedicated equipment financing can be used to purchase commercial kitchen equipment, including ranges, refrigeration units, dishwashers, fryers, ventilation systems, and POS systems. Equipment financing often supports longer repayment terms for major purchases.
Helpful: 0 / Not helpful: 0
Yes. SBG Funding offers SBA 7(a) financing, which is government-backed and typically provides larger amounts and longer repayment terms than conventional business loans. SBA financing are well-suited for restaurant acquisitions, major renovations, or significant equipment purchases. Qualification requirements are more stringent than for conventional loans, and SBA closings typically run 30 to 90 days. If a purchase has to close sooner, bridge capital can cover the gap and be repaid when the SBA financing funds. Contact our team to discuss whether SBA is the right fit for your situation.
Helpful: 0 / Not helpful: 0
Yes. Many restaurant owners use SBG Funding financing to cover the costs of opening a second location, including lease deposits, build-out, equipment, and initial working capital. A business term loan or SBA 7(a) financing is typically the best fit for expansion financing of this scale.
Helpful: 0 / Not helpful: 0
Your restaurant must have been in operation for at least 6 months to qualify for most SBG Funding programs. If you’re in your first 6 months, we recommend applying once you’ve reached that threshold with consistent monthly revenue. Early-stage restaurants with strong daily deposit patterns may qualify sooner, contact us to discuss your situation.
Helpful: 0 / Not helpful: 0
Ready to Fund Your Restaurant’s Next Chapter?
Whether you need to cover payroll between slow seasons, replace a piece of critical kitchen equipment, or open a second location, SBG Funding has restaurant financing options built for the food service industry. Apply online in minutes. No collateral, no hard credit pull, no obligation.